Global M&A Value Rises 15% as Megadeals Return
Global M&A value rose 15% in the first eight months of 2026, BCG reports, as megadeals reached 37 worldwide.
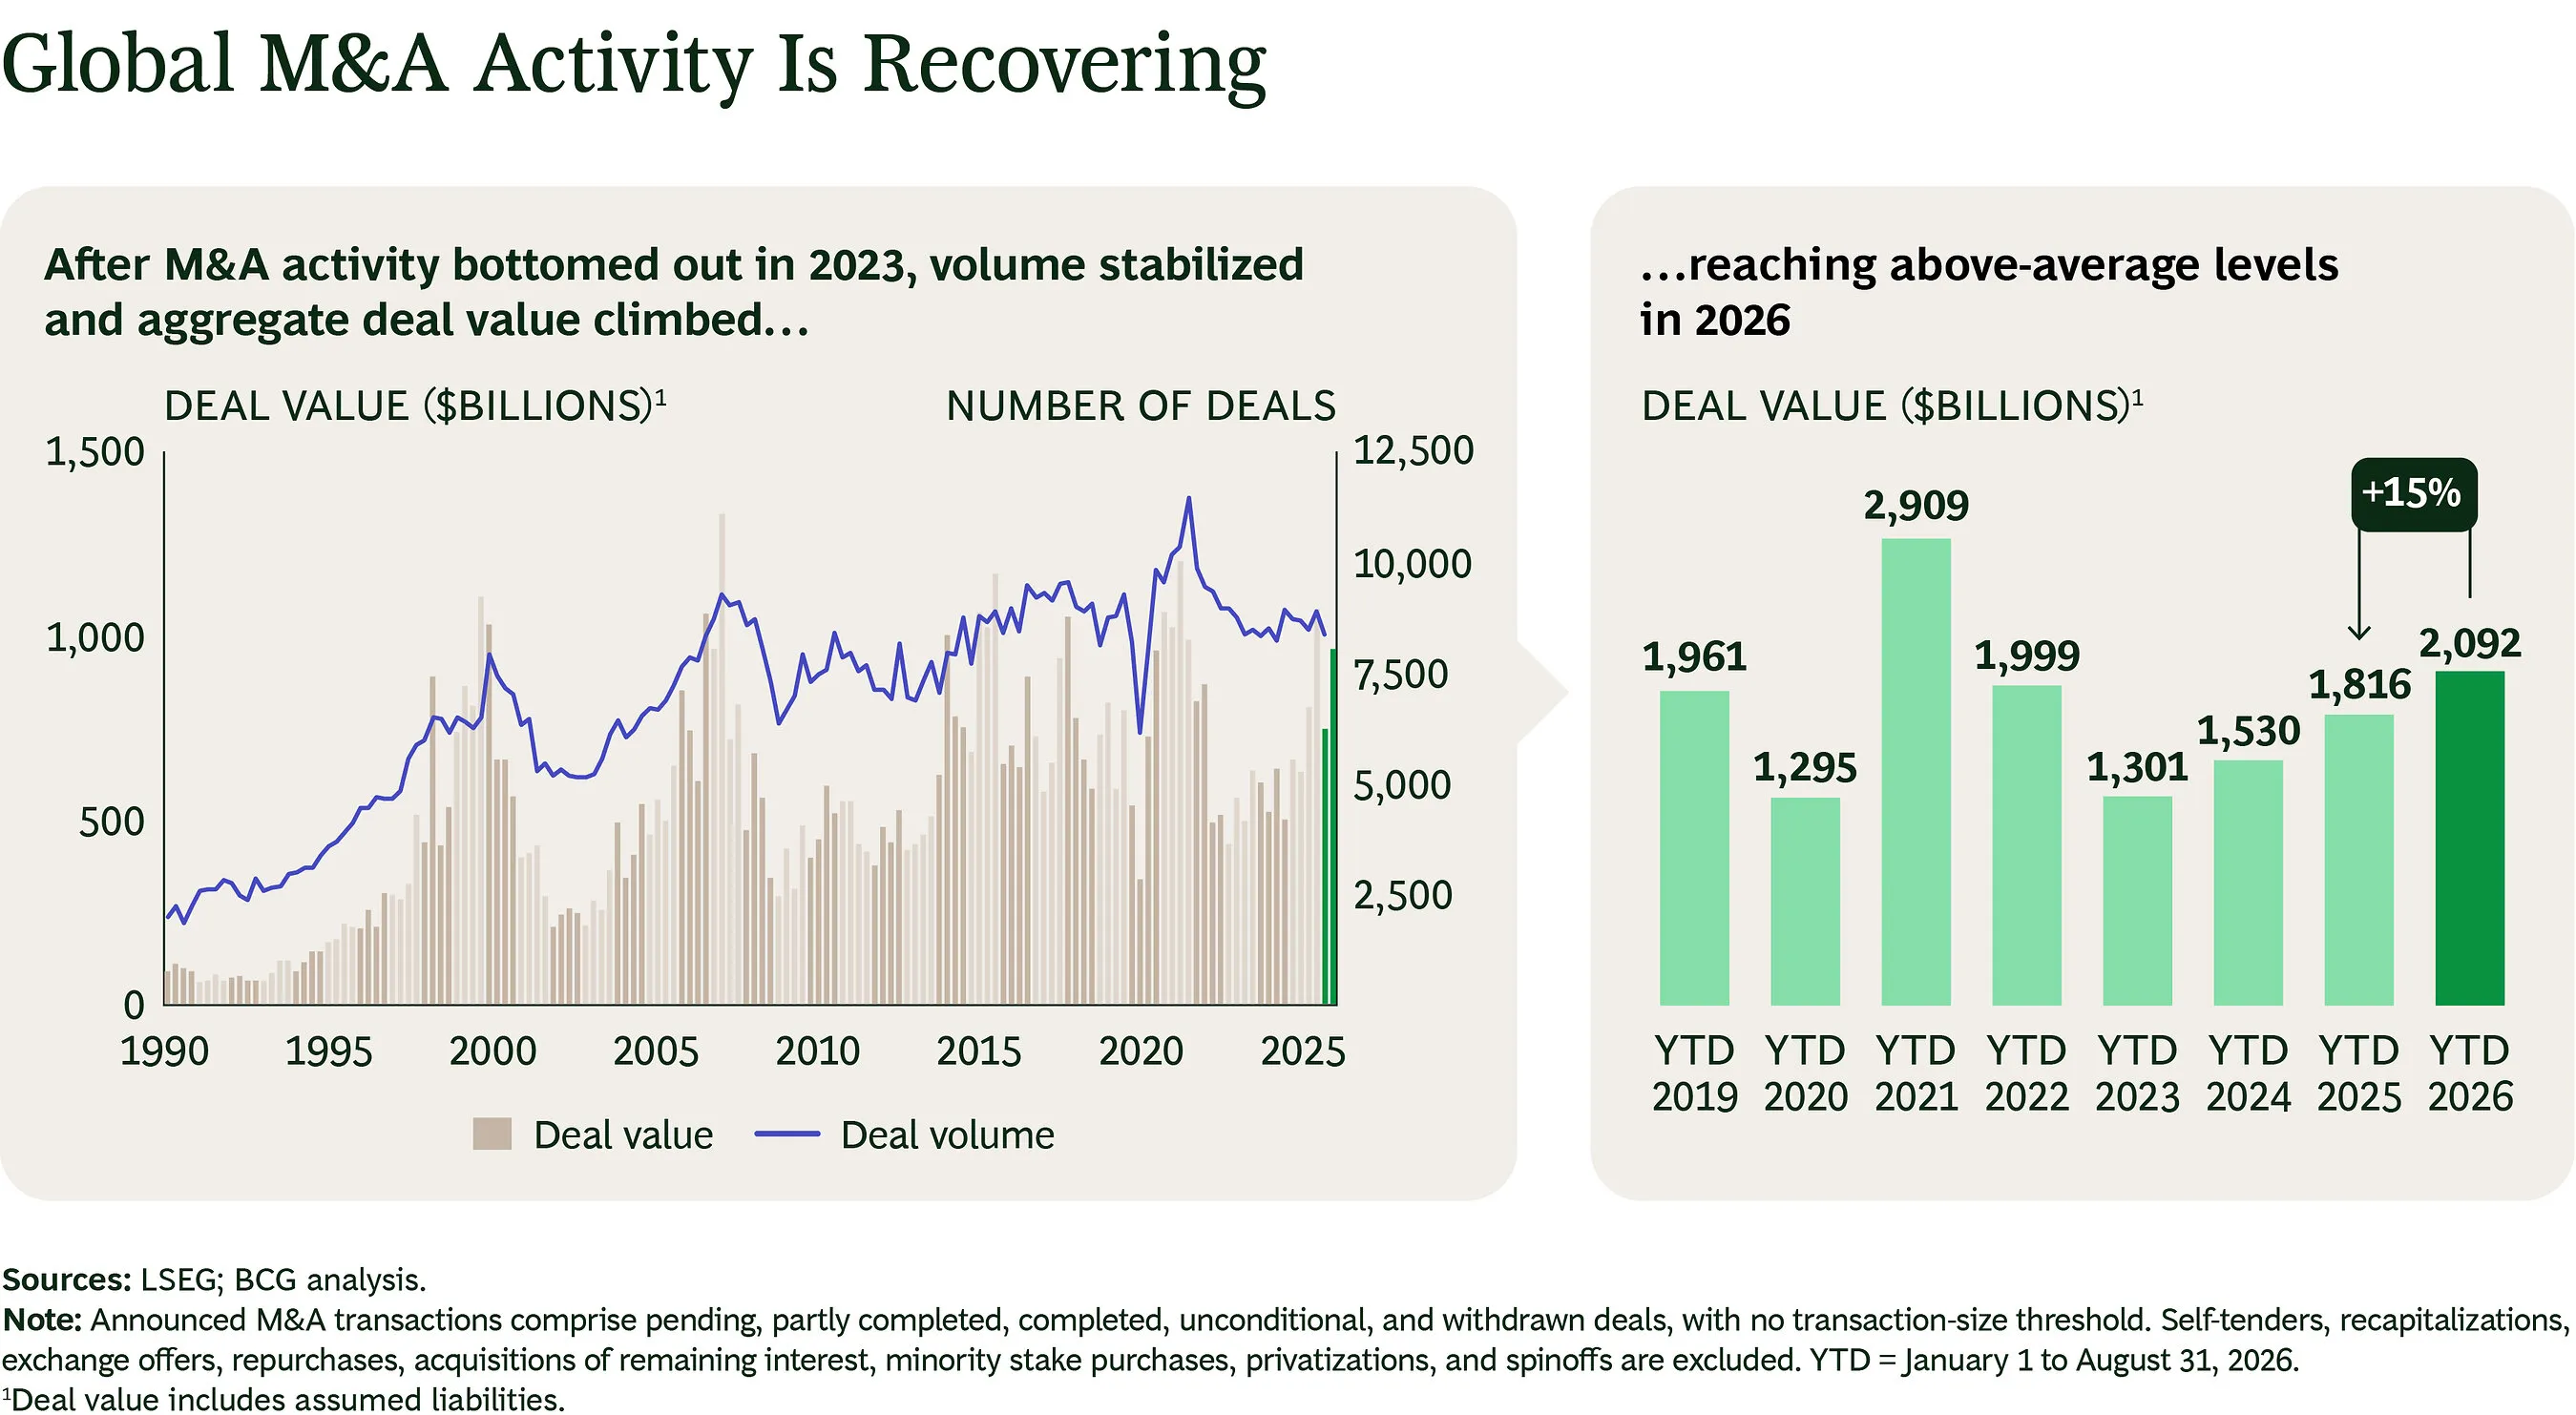
Boston Consulting Group has reported a 15% year-on-year rise in global M&A value during the first eight months of 2026, placing activity 11% above the ten-year average. The firm’s M&A Report 2026 shows that the number of transactions valued at $10 billion or more reached 37 between January and August, compared with 24 in the same period a year earlier and above the previous record of 32 in 2021. The recovery remains concentrated among the market’s largest transactions, while lower-value deal volumes are still below longer-term norms. BCG’s M&A Sentiment Index rose from 79 to 83 but remains below its long-term average of 100.
Recovery Concentrated In Large Deals
Transactions worth $1 billion or more are running above longer-term norms, while small-cap and midcap deal volumes remain below normal levels, even before accounting for inflation. BCG identifies asset readiness and market-clearing economics as the principal constraints on a broader recovery, while financing and organisational capacity are less restricted at a market level.
Jens Kengelbach, global leader of Mergers & Acquisitions at BCG and a coauthor of the report, said:
“Capital and strategic appetite are available. The bottleneck has shifted to execution: finding transaction-ready assets, bridging valuation gaps, and clearing the operational and regulatory hurdles required to close. Until more deals pass those tests, the recovery will remain concentrated at the top of the market.”
Sentiment Varies Across Sectors
Financial institutions and real estate recorded the strongest sentiment reading at 108, followed by health care at 100 and energy at 96. Industrials, consumer and technology registered lower readings of 66, 64 and 52 respectively, despite continued deal-value growth in technology and consumer markets.
Technology, media and telecommunications remained the largest sector by aggregate deal value, increasing 11% year on year. Consumer deal value rose 20% over the same period.
AI Creates Opportunity And Uncertainty
BCG found that AI is encouraging investment and deal activity in parts of the market while also complicating valuations for assets whose business models, revenue pools and competitive positioning may be affected by the technology. The report points to a correction in software company valuations and a pullback in private-equity software deal activity as early signs of this dynamic.
Daniel Friedman, global leader of Transactions & Integrations at BCG and a coauthor of the report, said:
“AI is doing two things to this market at once. It's a reason to do more deals and a reason some deals are harder to close. The companies that get furthest ahead are likely to be the ones that have actually worked out which is true for the asset in front of them.”
Regional And Regulatory Differences
North America accounted for more than half of aggregate global deal value, while Europe delivered the strongest percentage growth among major regions. Asia-Pacific activity declined.
BCG also highlighted a changing regulatory picture. Conventional antitrust enforcement may be less restrictive in some areas, but national-security screening, foreign-investment controls and foreign-subsidy reviews are increasingly influencing transaction terms, timing and economics.
Structures To Support More Transactions
The report identifies divestitures, carve-outs and private equity exits as potential sources of transaction-ready assets and capital for higher-priority businesses. It also points to minority investments, joint ventures, staged acquisitions, earnouts and rollover equity as structures that can help parties share valuation, technology, control and regulatory risk.
The full M&A Report 2026 examines the market’s deal outlook and performance in greater detail.